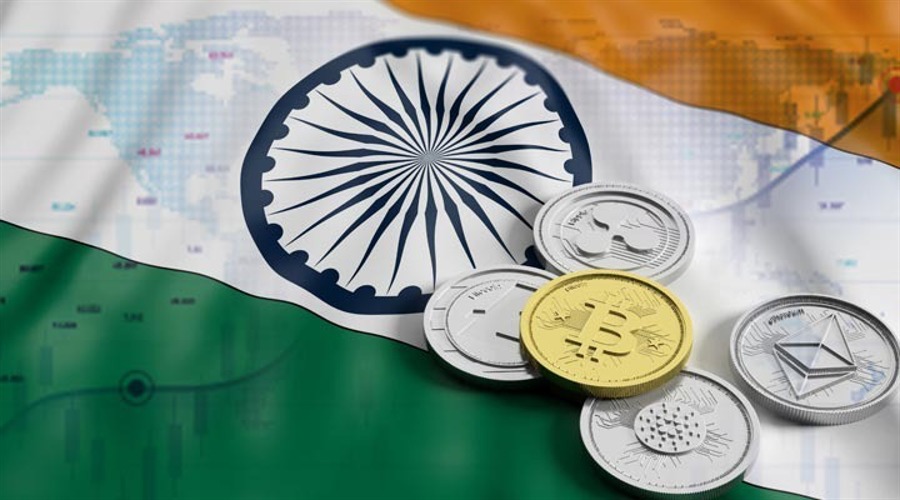
India is currently at the forefront of a significant investigation concerning substantial cryptocurrency-related cross-border transactions estimated at about $585 million. The Enforcement Directorate (ED) has zeroed in on various entities, including Mudrex, Saber.money, and the decentralized finance platform Instadapp. This extensive probe raises questions about the integrity and compliance of cryptocurrency operations within the country. Are these companies operating within the legal framework, or are they bending the rules to facilitate unauthorized transactions?
In this article, we’ll delve into the details of the investigation, highlighting the entities involved, the allegations made against them, and the broader implications for India’s cryptocurrency landscape. We will also touch upon recent measures taken by Indian authorities to regulate the crypto market more effectively.
Details of the Ongoing Investigation
The ED’s investigation focuses on RPFAS Technologies, the parent company of Mudrex and Saber.money. The agency claims these platforms enabled international transfers without the necessary approval from the Reserve Bank of India (RBI). Customers allegedly converted their fiat currency into stablecoins like USDT, which were then traded on various exchanges to send money outside of official banking channels.
Interestingly, the ED has identified foreign exchanges such as Binance and Bybit as part of this scheme, estimating the violations associated with RPFAS Technologies to be around $538 million. With such staggering figures, you might wonder: how do these financial maneuvers evade regulatory scrutiny for so long?
Involvement of Instadapp
The investigation also implicates Instadapp, known for its innovative financial solutions. The ED asserts that the founder, Sowmay Jain, managed this protocol from India, despite it being marketed as a U.S.-based operation. This raises critical questions about jurisdiction and regulatory compliance.
Reports indicate that revenues generated through stablecoins were funneled through various entities located in offshore tax havens such as the British Virgin Islands, Singapore, and Dubai. Ultimately, these funds were converted into fiat currency and sent back to India as payments for what the ED describes as “bogus software development and consultancy fees.” The alleged violations in this instance are valued at approximately $40 million.
Broader Implications for Cryptocurrency in India
India’s approach to cryptocurrency regulation has become increasingly stringent. In December 2023, authorities took steps to block access to nine offshore trading platforms, including Binance, due to concerns about anti-money laundering compliance. Subsequently, Binance and KuCoin registered with the Financial Intelligence Unit of India in 2024, with Binance facing a hefty fine of ₹188.2 million for alleged lapses in anti-money laundering protocols.
Additionally, in a separate crackdown, tax authorities targeted several Indian crypto exchanges in January 2022, uncovering around $9.4 million in unpaid taxes. With these actions, the Indian government is clearly signaling its intent to tighten controls over the burgeoning crypto market.
The Road Ahead for Cryptocurrency in India
As investigations like these unfold, one might ponder the future of cryptocurrency in India. Will stricter regulations drive innovation underground, or will they create a more stable environment for legitimate businesses? The ongoing scrutiny highlights the challenges facing both regulators and crypto enthusiasts in navigating this complex landscape.
In such a rapidly evolving sector, staying informed is crucial. Understanding the legal implications and the potential risks involved can help investors and businesses make better decisions. So, as you explore the world of cryptocurrency, keep an eye on these developments. They could have a lasting impact on the market and its participants in India.